en
Your Forecast Is Not a Plan. It Is a Test of Management Honesty.
A forecast is not a budget, target, or promise. It exposes assumptions, uncertainty, leading signals, and the decisions management will make when reality changes.
Read the viewEvery-other-day perspective for founders and capital
Clear, evidence-led views on fundraising, angel investing, founder strategy and the decisions that shape private markets.
Direct answer
The Mallick View is Zeeshan Mallick’s every-other-day authority publication. It explains fundraising, angel investing, founder strategy and private-capital decisions in clear language, using data, direct sources, tables and practical answers.
| Frequency | Every other day at 06:00 Dubai time |
|---|---|
| Languages | English, Spanish, Simplified Chinese and Hindi |
| Format | Clear answer, evidence, table, infographic, FAQs and direct sources |
| Author | Zeeshan Mallick |
A forecast is not a budget, target, or promise. It exposes assumptions, uncertainty, leading signals, and the decisions management will make when reality changes.
Read the viewRevenue growth is not enterprise value. McKinsey and Harvard evidence shows why founders and boards must design incentives around durable growth, quality, cash, customers, capability, and risk.
Read the viewSigning an acquisition does not create growth. Bain, McKinsey, and Harvard Business School show why value arrives only when customers, talent, systems, and synergies integrate.
Read the viewA one-page AI policy does not control models, data, access, vendors, or incidents. McKinsey, NIST, and IBM show why founders need an operating governance system.
Read the viewMost companies do not have a goal shortage. They have a goal system that rewards local scorekeeping while strategy fails. MIT, Google, and IBM show how to make goals frequent, ambitious, specific, transparent, and tied to outcomes.
Read the viewAn investor update is a short, repeatable operating control. It makes performance, risk, decisions, and asks visible before board or fundraising talks and saves time over ad hoc reporting.
Read the viewThe UK four-day-week pilot cut working time by 20% with no pay cut. Revenue stayed broadly stable while burnout, sick days, and staff departures fell. The lesson is not Friday off. It is process redesign.
Read the viewFounders should use board time to make decisions, set governance, and record accountability. Set two to three decisions, send materials early, pick directors to fill real weaknesses, and record owners and deadlines.
Read the viewA high NPS can be useful, but it does not prove product-market fit or future revenue. Bain, Springer, and Cambridge evidence shows founders must connect customer sentiment to renewal, expansion, payment, and profitable referrals.
Read the viewFounders should plan option pools as a role-and-cash system, not a slogan. Forecast roles, model grants, control approvals and valuation, explain tax, and review refreshes on a set cadence.
Read the viewGallup says only 20% of employees were engaged in 2025, while manager engagement fell to 22%. Founders who want culture to scale need a manager operating system, not another values workshop.
Read the viewAngel investors should set a portfolio system before saying yes. Define breadth, check size, follow-on reserves, diligence depth, and review rules so follow-ons are decisions from a plan, not gut reactions.
Read the viewA pitch that feels persuasive is not the same as evidence that raising more capital will strengthen a business. Unit economics — per‑unit profitability and customer economics — show whether growth compounds or simply accelerates cash burn.
Read the viewBooked sales that arrive after payroll, suppliers and taxes are not growth assets. Founders must treat payment terms and collection risk as an implicit financing cost and measure the working-capital gap.
Read the viewA polished board pack can look like governance. It often isn’t. Good governance forces the board and founder to surface constraints, options, evidence gaps, and the assumptions that would change the decision.
Read the viewAI pilots often read like product announcements. The true test of customer demand is a repeatable workflow, a named owner, measurable outcomes, persistent adoption, and the full cost of delivery. Without these, pilots are costs, not proof.
Read the viewVerizon says third-party involvement in breaches doubled to 30%. Founders who protect the firewall but ignore vendors, contractors, SaaS tools, and AI access are leaving the real attack surface unowned.
Read the viewFounders must decide: stay the indispensable bottleneck or design an operating system that runs without the founder in every room. Evidence from a large longitudinal study shows replacement of single-founder CEOs is complex — both risk and opportunity — and the right response is practical transferability, not ritual replacement.
Read the viewExpansion is often framed as a demand problem. This analysis reframes new markets as operating systems: legal, tax, labour, payment, and reporting capacity must be proven before marketing spend counts as demand.
Read the viewPartnerships become real growth channels only when they solve a specific customer problem, have a named owner with decision and budget authority, run a measurable pilot, and define the route from pilot to paid delivery. This evidence-led guide explains the decision criteria and the operational checklist founders must measure next. Not investment, legal, accounting, or tax advice.
Read the viewVenture debt can stretch capital — or it can convert a funding gap into a timed repayment problem. Founders must treat venture debt as a liability with a calendar: it follows equity, carries repayment schedules and covenants, and is evidence‑grounded in how startups actually finance themselves.
Read the viewHeadline ARR hides concentration risk. Before claiming repeatable growth, founders must disclose customer concentration, contractual resilience, and a credible path to diversification.
Read the viewA Harvard Business School study found CEOs held 37 meetings per week and spent 72% of work time in meetings. Microsoft reports work is more fragmented than ever. The founder guide to redesigning the calendar around decisions, customers, talent, and strategy.
Read the viewPendo found that 6.4% of features drive 80% of click volume in the average product, while almost 94% are untouched or ignored. The founder guide to stopping feature bloat, measuring adoption, and turning product output into customer value.
Read the viewProfessional services can unlock early enterprise sales, but they are not software growth. Benchmarkit: median subscription margin is 81%, professional services margin is 30%, and services above 15–20% of revenue can pull total margin below 77%. The metrics founders need before calling every dollar SaaS revenue.
Read the viewThe median SaaS company spends $2.00 to acquire $1 of new ARR and only $1.00 to create $1 of expansion ARR. High-NRR SaaS companies grow 2.5x faster. New logos are not the only growth channel: retention and expansion are the cheaper engine founders keep underfunding.
Read the viewA 1% price increase can raise operating profit by 8%, according to McKinsey. A 5% price cut needs 18.7% more volume just to break even. Most founders see the invoice discount, not the full pocket-price waterfall. The hard data on why discounting is not growth.
Read the viewCB Insights analysed 431 failed VC-backed companies: 43% failed due to poor product-market fit. Startup Genome analysed 3,200+ startups: 74% fail due to premature scaling. 93% of prematurely scaled startups never reach $100K monthly revenue. Properly scaled startups grow 20x faster. The data on why startups fail is unambiguous.
Read the viewStartup Snapshot surveyed 400+ founders and found 72% reported a mental health impact. 81% are not open about their stress. Founders who raise $30-70M are 83% more likely to sleep less than when they started. The psychological cost of building a company is real, measurable, and almost entirely hidden.
Read the viewA 2026 NBER study of 6,000 executives found that nearly 90% of firms say AI has had no impact on productivity. Companies have invested $250 billion in AI. Nobel laureate research predicts 0.5% productivity gain over 10 years. The layoffs are real. The productivity gains are not.
Read the viewHarvard Business School research found that 75% of VC-backed startups never return cash to investors. The industry self-reports 20-30%. The gap is not a rounding error — it is the difference between how VCs define failure and how founders experience it.
Read the viewForty percent of executive hires fail within 18 months. The true cost is 6 to 27 times the executive's annual salary. And 89% of failures are caused by attitude, not skill. Here is what the data says founders are getting wrong.
Read the viewReturn-to-office mandates are being issued by hundreds of companies. The data shows they do not improve performance, drive away top talent, and in 25% of cases are covert layoff strategies.
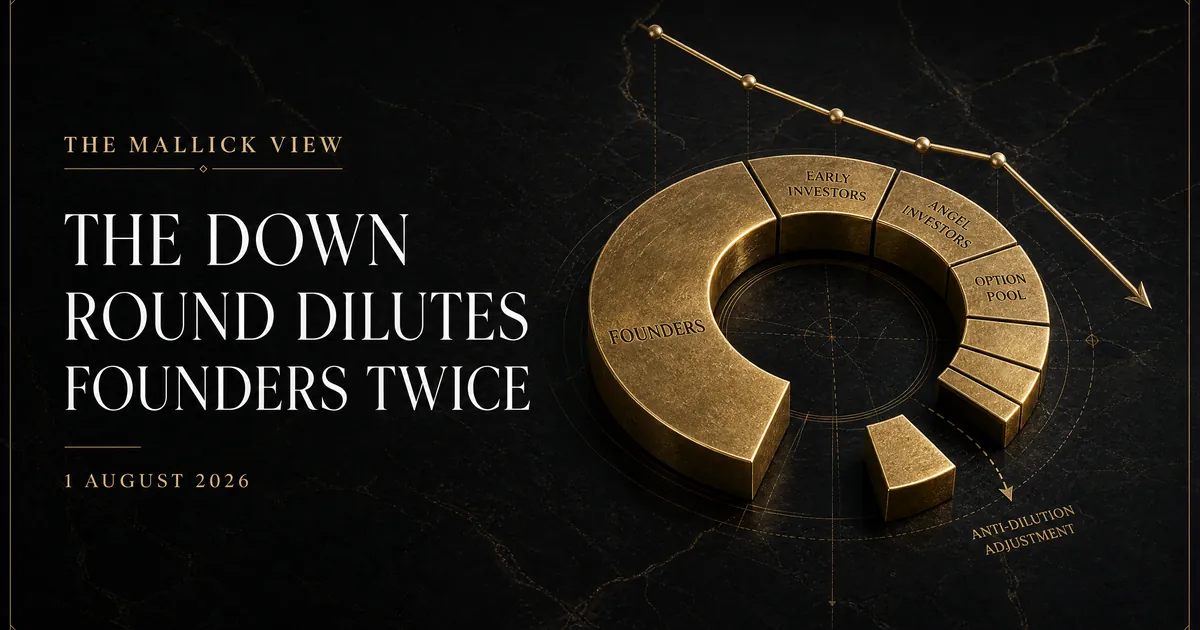
Read the viewDown rounds are rarer, not gone. Zee shows how new shares cause the first dilution and anti-dilution protection can move another 7.14 points away from common holders.
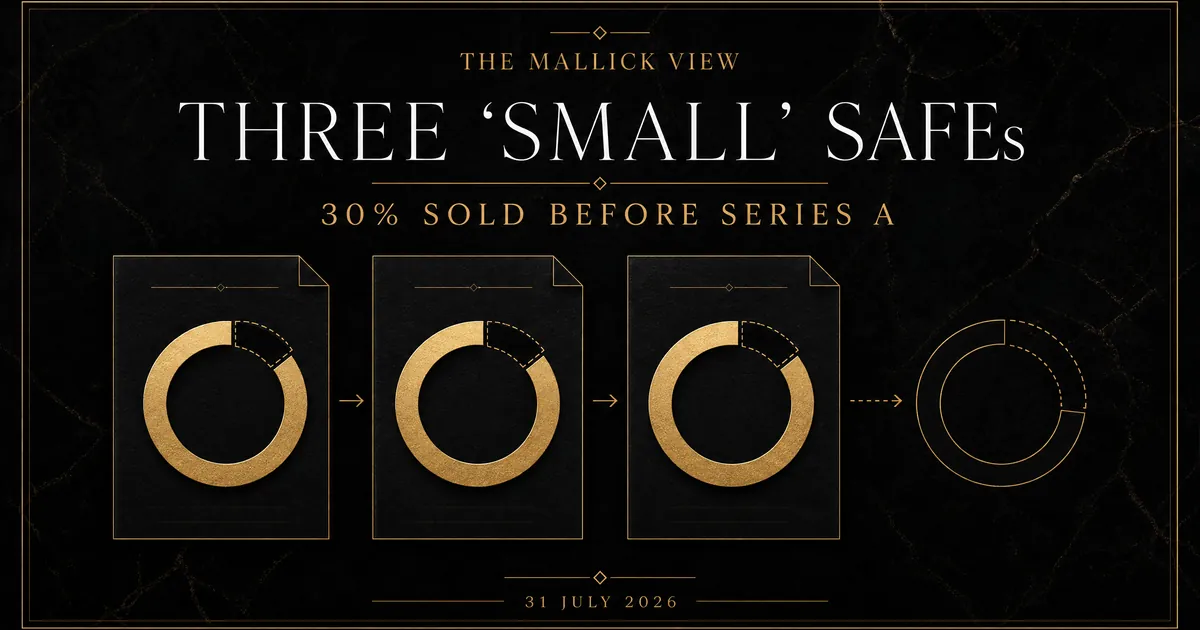
Read the viewA SAFE is not ownership-free bridge money. Zee shows how three simple post-money SAFEs can sell 30% before Series A and leave founders at 56% after the next round.
Read the viewA headline sale price is not the founder payout. Zee explains how liquidation preferences and participation can move millions away from common shareholders before an exit is shared.
Read the viewA large pre-money option pool can cut founder ownership before one employee is hired. Zee argues that founders should price a real hiring plan, not accept a standard percentage.
Read the viewZee argues that a board seat is not a relationship benefit. It is a governance right that can shape the CEO, strategy, funding and exit decisions.
Read the viewZee argues that a stack of simple SAFEs can quietly sell a large slice of a company before a priced round ever begins.
Read the viewZee argues that a headline valuation is not an exit plan: founders must model the preference stack before they celebrate the price.
Read the viewZee argues that founders should test an investor’s reserves, decision process and customer access before taking a famous name onto the cap table.
Read the viewA record seed valuation is not always a founder win. Zee explains why the right price must support the next proof point, not only flatter the first-round headline.
Read the viewA slow, vague investor can drain a founder’s time, runway and negotiating power. Zee’s rule is simple: seek qualified conviction, not endless soft interest.
Read the viewA high seed valuation can look like a win. Zeeshan Mallick argues that, without a clear proof plan, it can make the next round harder—not easier.
Read the viewRecord venture capital totals mask a brutal concentration. 73% of 2024 funding flowed to just 2% of startups. Founders without AI are starving.
Read the viewMaster Collective Newsletter
Receive concise perspectives on founders, capital and strategic growth.